
PNV
PNV has notably de-rated. Good – it was overvalued. But the stock is still on circa 12x sales.
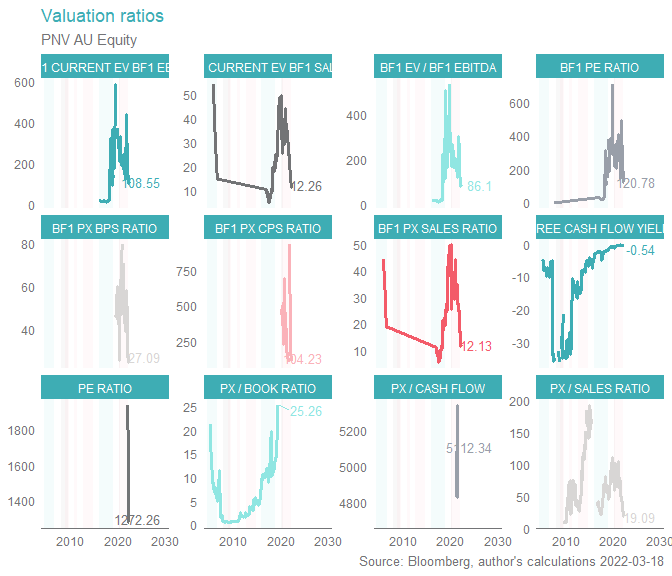
It remains pretty aggressive by assumption. The burst of operating profit (below) was only because…

…expenses fell. Falling expenses is typically bad news in a growing business. There could be a few good reasons for it, but one has finite bandwidth, and it’s just not worth diving deep, once you’ve uncovered a few hairs. The simplest explanation is that expenses will simply step back up in the next period, in which case we are back to the “unprofitable growth” dynamic.

And in a rising rate environment, there’s no need to be there.
NAN
NAN is a growth stock where the EBITDA just doesn’t rise. And, trades at ~9x revenues. Like PNV it appears they’ve got good products, and have demonstrated good market penetration, but for shareholders… I do see where the bulls are coming from, but other plays are easier.

SUL
Supercheap had a once in a lifetime pull forward in demand for its products…


…which bolstered margins…

…but the business is now over-earning, and whilst the stock price is back at pre-pandemic levels, it faces a material revenue and earnings headwind.
The balance sheet is okay, neither good or bad.

But with mortgage rates going back up, and higher oil prices, the hit to disposable income for discretionary items is potentially quite material, which brings the balance sheet back into focus.

It is easy enough to argue that the valuations are misleading, due to over-earning, and that negative momentum can easily cause the share price to overshoot to the downside.
Important Information: This document has been prepared by Aequitas Investment Partners Pty Ltd ABN 92 644 165 266 (“Aequitas”, “our”, “we”), a Corporate Authorised Representative (no. 1284389) of AIP FS Pty Ltd ABN 49 680 982 478 (Australian Financial Services Licensee no. 700016) and is for distribution within Australia to wholesale clients only.
This document is based on information available at the time of publishing, information which we believe is correct and any opinions, conclusions or forecasts are reasonably held or made as at the time of its compilation, but no warranty is made as to its accuracy, reliability or completeness. To the extent permitted by law, neither Aequitas nor any of its affiliates accept liability to any person for loss or damage arising from the use of the information herein.
Past performance is not a reliable indicator of future performance.
General Advice Warning: This document has been prepared without taking into account your objectives, financial situation or needs, and therefore you should consider its appropriateness, having regard to your objectives, financial situation and needs. Before making any decision about whether to acquire a financial product, you should obtain and read the relevant Product Disclosure Statement (PDS) or Investor Directed Portfolio Service Guide (IDPS Guide) and consider talking to a financial adviser.
Taxation warning: Aequitas is not authorised to provide tax (financial) advice and is not a registered tax agent. Investors should seek their own tax advice from a registered tax agent or a registered tax (financial) adviser if they intend to rely on this information to satisfy the liabilities or obligations or claim entitlements that arise, or could arise, under a taxation law. We recommend that you consult a registered tax agent or a tax specialist to confirm your taxation position.

